


Highest Refer and Earn Demat Account in India (2026): The Complete Earning Guide
Quick answer: The highest refer and earn demat account programs in India pay between ₹300 and ₹1,200 for every friend who opens a verified demat account through your link — far more than typical refer and earn apps that pay ₹10 to ₹100 in wallet coins. Demat referral programs pay real cash, per account, with no purchase required from your friend.
👉 Open your free demat account here and start referring today »
Table of Contents
- What Is a Refer and Earn Demat Account?
- Why Demat Refer and Earn Pays More Than Any App Referral
- Refer and Earn 500 vs Refer and Earn 1000: What's Realistic in India
- Highest Paying Refer and Earn Apps in India (Comparison Table)
- How to Get Started in Under 10 Minutes
- Refer and Earn Demat Account Without Trading — Is It Possible?
- How to Actually Get Referrals (11 Proven Methods)
- Realistic Earnings Math: ₹500, ₹1,000, ₹50,000 a Month
- Mistakes That Kill Your Referral Income
- Tax on Refer and Earn Income in India
- Refer and Earn 500 APK Files — A Serious Warning
- Frequently Asked Questions
What Is a Refer and Earn Demat Account?
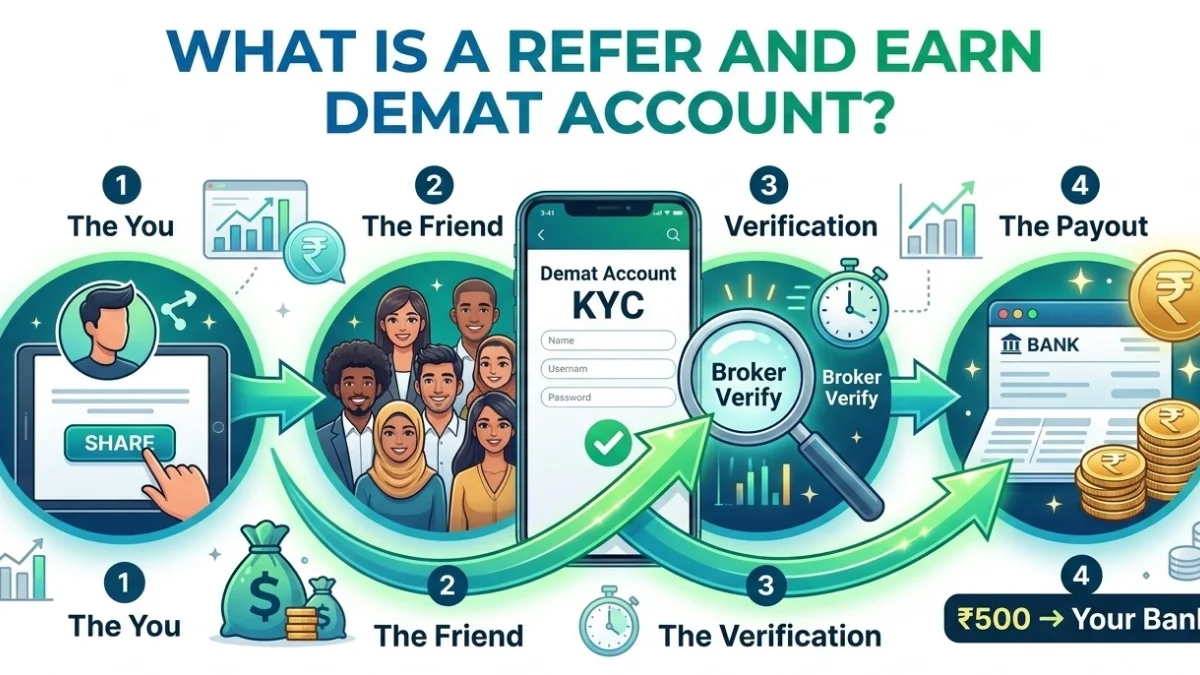
A refer and earn demat account is a stock broking account that pays you a cash reward every time someone opens their own demat account using your unique referral link or referral code. You share the link, your friend completes their KYC, the broker verifies the account, and the reward lands in your account — usually within one to two payout cycles.
Unlike an ordinary app refer and earn offer, where you might get ₹25 in wallet credit that can only be spent inside the app, a demat refer and earn program pays real, withdrawable money. That single difference is why people searching for the highest refer and earn demat account almost always end up here instead of on a cashback app.
Here's the structure in plain terms:
ElementWhat it means for youYour referral linkA unique tracked URL tied to your accountQualifying actionFriend opens and activates a demat account (KYC verified)RewardCash, paid per successful accountCapUsually unlimited referralsCost to your friend₹0 — account opening is free
The last line is the most important one. Your friend is not buying anything. They are opening a free investment account they can genuinely use for stocks, IPOs, mutual funds and SIPs. That's what makes this one of the cleanest referral and earn apps categories in India — nobody has to spend money for you to get paid.
👉 Get your referral link — open a free demat account in 5 minutes »
Why Demat Refer and Earn Pays More Than Any App Referral
If you've ever tried a food-delivery or cashback referral app, you know the pattern: ₹50 for the first invite, ₹20 for the next, and then suddenly the offer "has expired for your account."
Demat referral programs work on completely different economics. Understanding why will change how you think about this whole category.
1. The lifetime value of a customer is enormous
A broker earns brokerage every single time your referred friend places a trade. Over the life of an active account, that can be thousands of rupees in revenue. Paying you ₹500 or ₹1,000 once is a rounding error against that. A food app, in contrast, might earn ₹15 margin on an order — so it can only afford to pay you ₹10.
2. Regulated onboarding filters out fraud
Every demat account requires PAN, Aadhaar, a bank account and a live video or selfie verification. That makes fake referrals nearly impossible, which means brokers can afford to be generous with genuine referrers. Most refer and earn apps in India must keep payouts tiny precisely because their sign-ups are trivially easy to fake.
3. Payouts are cash, not coins
This is the quiet killer. Search for "refer and earn 500" and most results lead to apps that credit 500 coins, points or scratch-card value — redeemable only against a purchase, often with a minimum spend. Demat referral rewards are credited as money to your linked account or as a direct bank transfer.
4. There is no practical ceiling
Serious referrers in India run this as a proper business — YouTube channels, Telegram groups, finance blogs — and do dozens of accounts a month. Almost no consumer refer and earn app allows that kind of scale without banning you.
The bottom line: if your goal is genuine income rather than pocket change, a demat account referral program is the highest-paying option available to an ordinary person in India, with no inventory, no investment and no sales pitch.
Refer and Earn 500 vs Refer and Earn 1000: What's Realistic in India
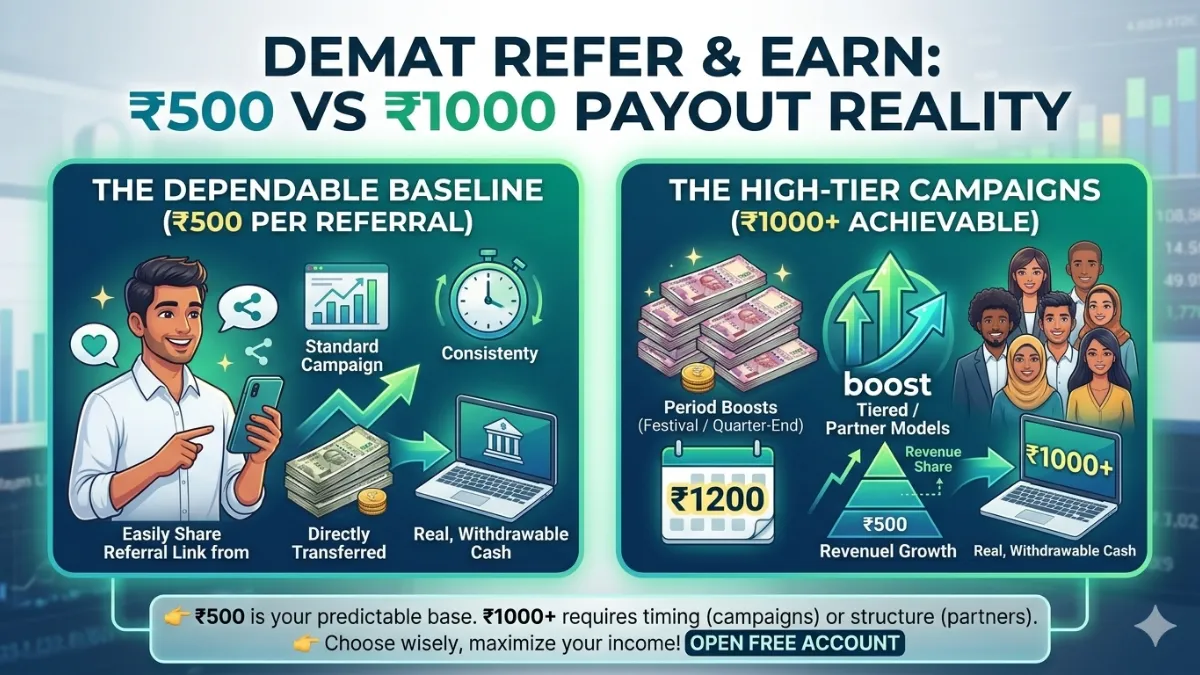
Two of the most searched phrases in this space are "refer and earn 500" and "refer and earn 1000." Let's be honest about what each actually means. They might includes upi apps, refer earn money apps, referral programs, referral rewards etc
The "refer and earn 500" reality
Searches for refer and earn 500 app, refer and earn 500 in India and refer and earn apps 100 Rupees almost always land on one of three things:
- Cashback and wallet apps — pay ₹10–₹100, usually as restricted credit.
- Gaming and survey apps — advertise ₹500 but gate it behind wagering or a long task chain.
- Demat and fintech accounts — actually pay ₹500 or more in real cash.
Only the third category delivers on the headline number consistently. A refer and earn 500 demat account offer is real: you refer one person, that person opens an account, you receive a payout in that range depending on the live campaign.
The "refer and earn 1000" reality
A refer and earn 1000 demat account payout is genuinely achievable, but it usually comes in one of two forms:
- A campaign period. Brokers periodically run boosted offers — festival campaigns, quarter-end pushes, new-product launches — where per-account payouts climb well above the base rate, sometimes to ₹1,000–₹1,200.
- A tiered or partner structure. Some brokers pay a base amount per account plus a revenue share on the brokerage your referred client generates. In that model your first ₹500 arrives immediately and the rest accumulates over months.
So: ₹500 per referral is the dependable baseline. ₹1,000+ is achievable during campaigns or through partner-tier structures. Anyone promising a flat ₹1,000 forever, guaranteed, is selling you something.
👉 Check the live referral payout — open your account free »
Highest Paying Refer and Earn Apps in India (Comparison Table)
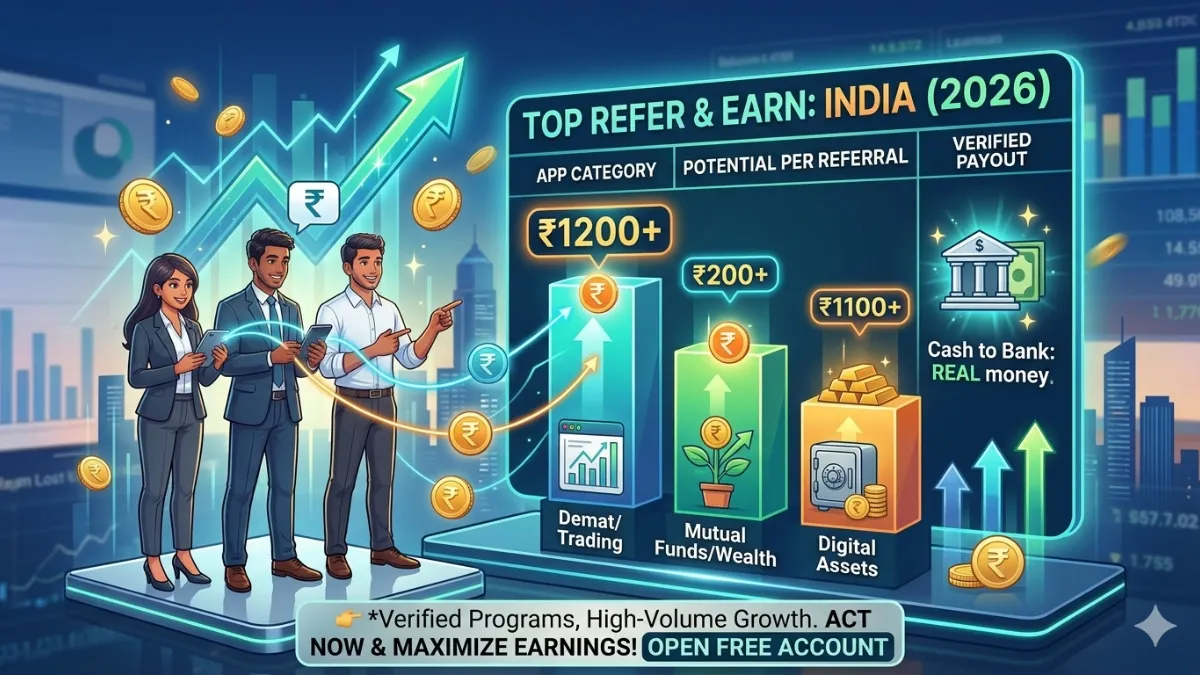
Here's how the main categories stack up. Figures are indicative ranges for 2026 — always confirm the live offer inside the app, because referral terms change frequently.
- Demat / Broking Accounts
- Typical payout per referral: ₹300 – ₹1,200
- Paid in: Cash
- Friend must spend?: No
- Realistic monthly ceiling: ₹10,000 – ₹1,00,000+
- Credit Card Referrals
- Typical payout per referral: ₹500 – ₹2,000
- Paid in: Cash / vouchers
- Friend must spend?: Yes (requires approval + minimum spend)
- Realistic monthly ceiling: Low (due to hard approval rates)
- Payment & UPI Apps
- Typical payout per referral: ₹25 – ₹200
- Paid in: Wallet cash
- Friend must spend?: Usually requires a first transaction
- Realistic monthly ceiling: ₹2,000 – ₹5,000
- Food Delivery Apps
- Typical payout per referral: ₹75 – ₹150
- Paid in: Discount coupon
- Friend must spend?: Yes (must place their first order)
- Realistic monthly ceiling: ₹1,000 – ₹3,000
- Shopping / Cashback Apps
- Typical payout per referral: ₹10 – ₹100
- Paid in: Restricted credit
- Friend must spend?: Yes
- Realistic monthly ceiling: ₹500 – ₹2,000
- Gaming Apps
- Typical payout per referral: "₹500" advertised
- Paid in: Locked in-app coins
- Friend must spend?: Yes
- Realistic monthly ceiling: Usually unredeemable
Why demat wins on every axis that matters
- Zero friction for your friend. Free account, no deposit needed to open, no purchase.
- Real money, not credit. Withdrawable to a bank account.
- Unlimited scale. No hidden cap after three invites.
- A genuinely useful product. You're not spamming people with a discount code — you're getting them started on investing, which most Indians should be doing anyway.
That last point is what separates people who earn ₹500 from people who earn ₹50,000. If you believe in what you're recommending, referrals stop feeling like begging.
How to Get Started in Under 10 Minutes
You cannot refer anyone until you hold the account yourself. Here's the full sequence.
Step 1 — Open your own demat account (free)
Keep these four things ready:
- PAN card
- Aadhaar linked to your mobile number (for OTP-based e-KYC)
- Bank account details — account number and IFSC, or a cancelled cheque
- Signature on white paper and a selfie
👉 Start here — open your free demat account »
Step 2 — Complete e-KYC and verification
Aadhaar OTP verification, an in-person verification video (a 10-second selfie video in most cases), and bank validation. Most accounts are activated within 24 hours; many within a couple of hours.
Step 3 — Find your referral link
Inside the app, open the menu (usually the profile icon in the top-left) and look for Refer & Earn or Invite Friends. Your unique link and referral code are generated there. Copy it.
Important: your friend must open the account through your link, on the app, and must not have held an account with that broker on the same PAN before. This is the number one reason referrals fail to track.
Step 4 — Share it where people actually are
Not a mass WhatsApp blast. See the eleven methods below.
Step 5 — Track and get paid
Most apps show a referral dashboard with three states: clicked, KYC pending, account opened. Payouts are typically credited on a fixed cycle — often twice a month — after a short holding period once the account is verified.
Step 6 — Help your referrals actually use the account
An account that is opened and never used sometimes doesn't qualify, depending on the campaign terms. Spend five minutes helping your friend place their first small investment. It protects your payout and it's the right thing to do.
Refer and Earn Demat Account Without Trading — Is It Possible?
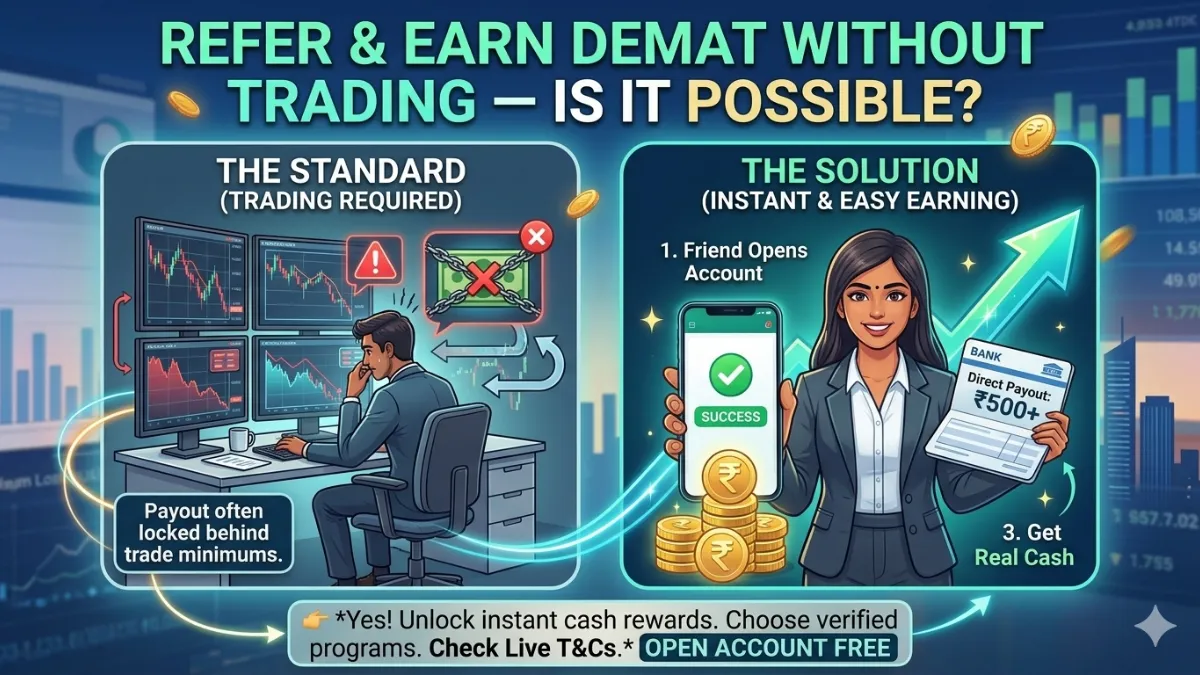
This is one of the most common searches in the category, and the answer is: yes, in most cases.
Here's the nuance, because it matters.
What's always required
- The referred person must open the account through your link.
- KYC must be completed and the account activated.
- The PAN must be new to that broker.
What's sometimes required
- A first trade or first investment. Some campaigns split the reward: a portion on account activation, the rest after the first trade or first F&O trade. Others pay the full amount on activation alone.
- A minimum funding amount. Less common, but it appears in certain boosted offers.
The honest answer
For a standard, non-boosted referral, you generally earn on account opening and activation without your friend needing to trade. For the higher refer and earn 1000 style campaigns, there's more often a trading or funding condition attached to the bonus portion.
So if someone asks "do I have to trade?" — tell them the truth: no, you don't have to trade, but opening the account and putting even ₹100 into a mutual fund or an ETF makes the account real and useful. That's a much better pitch than "just open it for my bonus," and it converts better too.
👉 Open your account now — free, no trading required »
How to Actually Get Referrals: 11 Proven Methods
This is the section most articles skip. Anyone can tell you to "share your link." Here's what actually produces accounts.
1. Start with the "already asking" list
Make a list of every person who has asked you — even casually — about the stock market, SIPs, IPOs, gold ETFs or "where should I put my salary savings." These people convert at a very high rate because they already have intent. You're not selling; you're answering.
2. YouTube Shorts and Instagram Reels
Short, specific, useful videos outperform everything else in Indian finance content. Ideas that work:
- "How to apply for an IPO in 60 seconds"
- "₹500 per month SIP — what it becomes in 20 years"
- "3 things nobody tells you before opening a demat account"
Put the link in the bio and pinned comment. One video that gets 50,000 views can produce dozens of accounts.
3. A blog post (like this one)
Search traffic compounds. Someone searching "highest refer and earn demat account" or "best demat account for beginners" at 11 p.m. is ready to act. A single well-ranked article can generate referrals for years with zero ongoing effort.
4. Telegram and WhatsApp communities
Not spam — value. Run a small group where you post market updates, IPO calendars and beginner explainers. Put your link in the group description. People join for the content and open accounts because they trust you.
5. Quora and Reddit answers
Answer questions like "Which demat account is best for beginners in India?" with a genuinely useful, balanced answer. Disclose that your link is a referral link. Honest disclosure massively increases conversion — people appreciate being told.
6. College and workplace groups
First-job earners are the single highest-converting demographic in India for demat accounts. They have new income, no investment plan, and high curiosity.
7. Help people apply for IPOs
IPO season is the best conversion window in the Indian market. "There's an IPO open this week, you need a demat account to apply, here's mine, it takes ten minutes" is one of the highest-converting sentences in this entire business.
8. Family WhatsApp groups — done right
Instead of dropping a raw link, post something useful: "Uncle, here's how to check if your old shares are lying in an unclaimed folio." Value first, link second.
9. Offer to sit with them
The single biggest barrier to opening a demat account is not motivation — it's the KYC process feeling intimidating. Offering fifteen minutes on a call to walk someone through it converts hesitant people into completed accounts.
10. Pinterest and LinkedIn
Underrated in Indian finance. LinkedIn in particular is full of salaried professionals who want to start investing and don't know where.
11. A simple landing page
One page: what a demat account is, why they should open one, a comparison table, and a big button. Send all your traffic there instead of to a raw link. Conversion typically improves substantially.
👉 Set up your account and start with method #1 today »
Realistic Earnings Math: From ₹500 to ₹50,000 a Month

Let's replace hype with arithmetic. Assume a conservative average payout of ₹500 per successful account.
Here is the breakdown of the potential income scaling, structured into a clean, one-by-one list:
- 1 Account per Month
- Monthly income: ₹500
- Annual income: ₹6,000
- Effort level: One friend, casually
- 4 Accounts per Month
- Monthly income: ₹2,000
- Annual income: ₹24,000
- Effort level: Family and close friends
- 10 Accounts per Month
- Monthly income: ₹5,000
- Annual income: ₹60,000
- Effort level: Active WhatsApp / Telegram sharing
- 25 Accounts per Month
- Monthly income: ₹12,500
- Annual income: ₹1,50,000
- Effort level: Regular short-form video content
- 50 Accounts per Month
- Monthly income: ₹25,000
- Annual income: ₹3,00,000
- Effort level: Small YouTube channel or ranked blog
- 100 Accounts per Month
- Monthly income: ₹50,000
- Annual income: ₹6,00,000
- Effort level: Established finance creator
The realistic conversion funnel
Don't plan around link clicks. Plan around this chain:
100 people see your link
 ↓ 20 click it                    (20% click rate)
 ↓ 8 start the KYC process        (40% of clicks)
 ↓ 5 complete and activate        (60% of starts)
= 5 payouts = ₹2,500
Meaning: roughly 100 genuine impressions produce about 5 accounts. To hit ₹25,000 a month you need around 1,000 real impressions monthly — one decent Reel, or one modestly ranked blog post.
The compounding part people miss
If your broker has a revenue-share component, an account you refer today can keep paying you for years as that person trades. Fifty accounts referred in year one can still be generating income in year three. That's the difference between a side hustle and an asset.
7 Mistakes That Kill Your Referral Income
Mistake 1: Mass-blasting your link
WhatsApp and Telegram both throttle accounts that send identical links repeatedly. You'll get restricted before you get paid. Personalise every message.
Mistake 2: Letting them open the account any other way
If your friend searches the broker's name on Google and opens the account directly, you get nothing — even if you were the reason they did it. Send the link. Watch them click it. Most brokers also require the account to be opened through the app, not a desktop browser.
Mistake 3: Referring someone who already has an account there
The PAN check is absolute. If that PAN has ever held an account with that broker, no reward is paid. Ask first: "Do you already have an account with them?"
Mistake 4: Promising things the offer doesn't include
Never tell someone they'll get ₹500 for signing up unless the live offer actually says so. Broken promises destroy your credibility, and your credibility is the entire business.
Mistake 5: Abandoning them mid-KYC
Most drop-offs happen at the bank verification or IPV step. A single follow-up message — "did it go through?" — recovers a surprising number of incomplete applications.
Mistake 6: Ignoring the offer terms
Read the terms every quarter. Payout amounts, holding periods, and qualifying conditions all change. Referrers lose money by running on last year's assumptions.
Mistake 7: Not disclosing that it's a referral link
Disclosure is both an ethical requirement and a conversion advantage. "Full disclosure, this is my referral link — I get a small reward and you get a free account" performs better than hiding it. People are not stupid, and they reward honesty.
Tax on Refer and Earn Income in India
This is not optional reading if you're doing this at scale.
How referral income is treated
Referral rewards are generally taxable as "Income from Other Sources" and are added to your total income, taxed at your applicable slab rate. Some platforms may treat larger referral incentives under a business-income head if the activity is regular and systematic — if you're earning meaningfully, get this classified correctly.
TDS
Platforms commonly deduct TDS under Section 194R (benefits or perquisites from business or profession) or 194H (commission and brokerage), depending on how the arrangement is structured, once payouts cross the prescribed threshold in a financial year. The deducted amount shows up in your Form 26AS and can be adjusted against your final tax liability.
What you should do
- Keep a simple monthly record of payouts received.
- Download your Form 26AS and AIS before filing.
- Report the income in your ITR even if TDS was already deducted.
- If you're crossing a lakh or more annually, talk to a CA once. It costs little and prevents problems.
This section is general information, not tax advice. Rules and thresholds change — confirm the current position with a qualified chartered accountant or on the Income Tax Department's website before filing.
"Refer and Earn 500 APK" — A Serious Warning
There is heavy search volume for "refer and earn 500 apk," and it deserves a blunt answer.
A legitimate referral program never requires you to download an APK file from a third-party website. Anything distributed as a sideloaded APK promising guaranteed ₹500 referral payouts should be treated as hostile until proven otherwise.
What these APKs typically do
- Harvest your data — SMS access means they can read your banking OTPs.
- Never pay out — the wallet balance rises, the withdrawal always fails one verification short.
- Run pyramid mechanics — you only get paid when your recruits recruit, which collapses by design.
- Install malware — banking trojans in India are commonly distributed exactly this way.
How to tell a genuine program from a scam
Here is the comparison between genuine and scam apps, structured into a clean, one-by-one list:
- App Sourcing
- Genuine: App on Google Play / App Store
- Scam: APK from a random site or Telegram
- Regulation & Registration
- Genuine: Company is SEBI/RBI regulated
- Scam: No regulator, no registered entity
- Verification Requirements
- Genuine: KYC required
- Scam: "No KYC, instant money"
- Payout Mechanism
- Genuine: Payout to your bank account
- Scam: Payout to an in-app wallet that never clears
- Earning Criteria
- Genuine: You earn per verified customer
- Scam: You earn per person you recruit
A demat account referral program passes every test on the left. The broker is a SEBI-registered entity, the app is on the official stores, KYC is mandatory, and payment goes to a verified bank account.
👉 Use a SEBI-regulated broker — open your free demat account »
Frequently Asked Questions
Which demat account has the highest refer and earn payout in India?
Demat referral payouts in India typically range from ₹300 to ₹1,200 per successfully opened account, and the leader changes as brokers run campaigns. Base rates cluster around ₹300–₹500, with boosted campaign periods pushing toward ₹1,000–₹1,200. Always check the live offer inside the app, since terms are revised frequently.
Can I really do refer and earn 500 with a demat account?
Yes. Refer and earn 500 demat account offers are among the most reliable ₹500 payouts available in India, because they're backed by regulated brokers paying real cash rather than in-app coins.
Is refer and earn 1000 for a demat account genuine?
It can be, during campaign periods or through partner structures that combine a base payout with a revenue share. It is not usually a permanent flat rate — treat any claim of a guaranteed, permanent ₹1,000 with caution.
Do I need to trade to earn referral rewards?
Usually no. Standard referral rewards are paid on account opening and activation. Some higher-value campaigns attach a first-trade or funding condition to the bonus portion, so read the current terms.
How long does the referral reward take to arrive?
Typically after a short holding period once the referred account is verified — commonly around a week — with credits released on a fixed cycle, often twice a month.
Is there a limit on how many people I can refer?
Most demat referral programs do not cap the number of referrals, which is exactly why they scale far better than ordinary refer and earn apps in India.
What if my friend opens the account without my link?
You get nothing. Tracking is entirely link-based. They must click your link and complete the process through the app.
Can I refer my own family members?
Generally yes, provided each person uses their own PAN, their own bank account and their own mobile number. Creating accounts on someone else's behalf or using duplicate details violates the terms and can void your rewards permanently.
Is refer and earn income taxable in India?
Yes. It's generally taxable as income from other sources at your slab rate, and TDS may be deducted by the platform above the prescribed threshold. Report it in your ITR.
What documents does my friend need?
PAN, Aadhaar linked to their mobile number, bank account details, a signature image and a selfie or short verification video.
Are refer and earn apps paying 100 rupees worth it?
Only as pocket money. At ₹100 per referral you need fifty conversions to match ten demat referrals — and most of those apps pay in restricted credit rather than cash.
What's the fastest way to get my first referral?
Ask one person who has already told you they want to start investing. Send them the link, then stay on the phone while they complete KYC. That's your first payout, usually within 48 hours.
The Honest Conclusion
If you search "highest refer and earn demat account," you're really asking one question: where does a normal person in India actually make meaningful money from referrals?
The answer isn't a cashback app. It isn't a gaming APK promising ₹500. It's a regulated broking account, where the economics genuinely support paying you hundreds of rupees per person, in real cash, with no cap and nothing for your friend to buy.
But the money follows the trust. The people who earn ₹500 a month are sharing a link. The people who earn ₹50,000 a month are helping people start investing, and getting paid for it. That's the whole difference.
Start with your own account — you can't refer anyone until you have one.
👉 Open your free demat account now and get your referral link »